
How the Rule of 72 Can Expose a Bad CD Rate in Seconds
Most people accept a certificate of deposit rate without ever asking the one question that matters most: how long will this actually take to double my money?
Why CD shoppers rarely think in doubling time
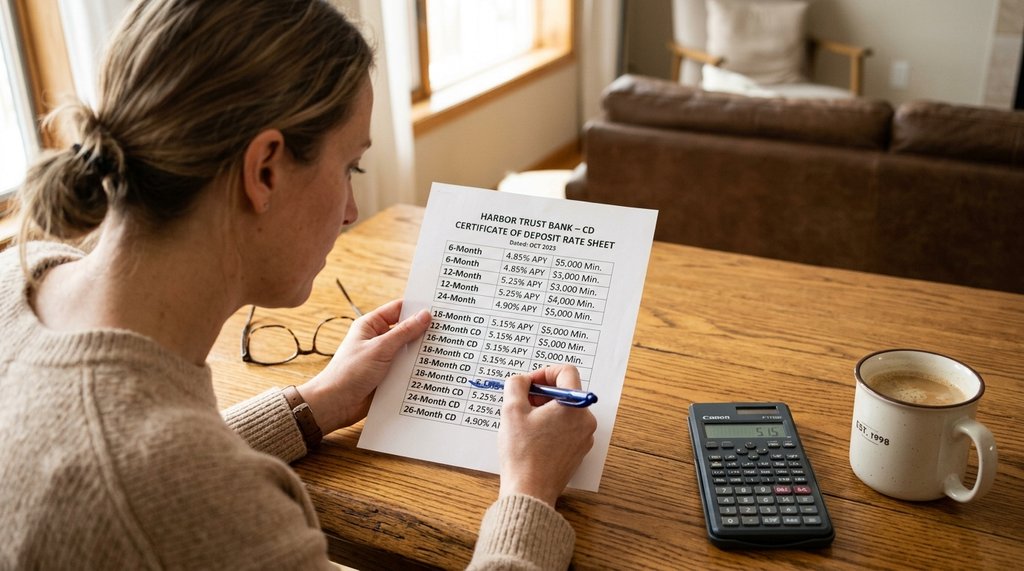
Banks advertise CD rates as annual percentage yields, and most depositors compare those numbers the way they compare gas prices: bigger is better, end of story. But a 4.2% APY and a 3.8% APY look deceptively similar on a rate sheet. The real difference only becomes obvious when you think in years, not percentages.
The Rule of 72 reframes the question instantly. Divide 72 by your interest rate, and you get the approximate number of years it takes your money to double. At 4.2%, that is about 17.1 years. At 3.8%, it is about 18.9 years. That single extra percentage point shaves almost two years off your doubling time, which on a $50,000 deposit is the difference between ending up with $100,000 around 2043 versus 2045.
The 3-second test every saver should run before locking in a rate
Before signing any CD agreement, grab your rate and divide 72 by it. If the answer is longer than your personal financial horizon, the CD is probably the wrong product. Someone saving for a home purchase in 8 years should not be content with a 3% rate that needs 24 years to double principal. Try the rule of 72 calculator to see your own numbers.
This is where the rule earns its keep as a sanity check rather than a bragging-rights formula. A 5-year CD at 4.5% yields a doubling time of 16 years. Fine for retirement savings, but not for medium-term goals. Running this check with a rule of 72 calculator takes a few seconds and forces you to confront whether the timeline actually matches your plan.
The math also works in reverse. If you need your money to double in 10 years, you need a rate of at least 7.2%. That tells you immediately that cash-based instruments alone probably will not get you there, and you need to have a conversation about equities or other growth assets.
When inflation swallows the number you thought was safe
Here is the part most CD marketing conveniently omits. You should run the Rule of 72 twice: once on your nominal rate, and once on inflation. If your CD pays 4.2% but inflation is running at 3.1%, your real return is roughly 1.1%. At that rate, the real purchasing power of your deposit takes about 65 years to double.
That is not a dramatic exaggeration; it is basic arithmetic. Locking $50,000 into a five-year CD that barely outpaces inflation means your money treads water in real terms. The Rule of 72 makes this brutally clear in a way that a yield comparison chart rarely does.
Checking both numbers before committing to a long lock-up period is especially worth doing when central bank rate trajectories are uncertain. Rates that look attractive today may look modest within the life of a 5-year instrument, and knowing your real doubling time helps you decide whether flexibility is worth more than a slightly higher yield.
Using the rule to compare across account types, not just rates
The Rule of 72 is not limited to CDs. You can apply the same check to a high-yield savings account, a money market fund, or the long-run historical average of an index fund. The S&P 500 has averaged roughly 10% annually over long periods. At that rate, the doubling time is about 7.2 years. A high-yield savings account at 4.5% takes 16 years.
That comparison does not mean you should move emergency savings into equities. It means you should be clear-eyed about what each account is actually doing for you, and whether you have the right mix. The rule puts all of those options onto the same simple scale: years to double.
Doing this comparison consistently, every time you open or renew an account, builds a habit of thinking about money in terms of time rather than just yield percentages. Small rate differences that look trivial on a rate sheet compound into meaningful gaps over a decade.