
Do High-Yield Savings Rates Still Beat Inflation in 2026?
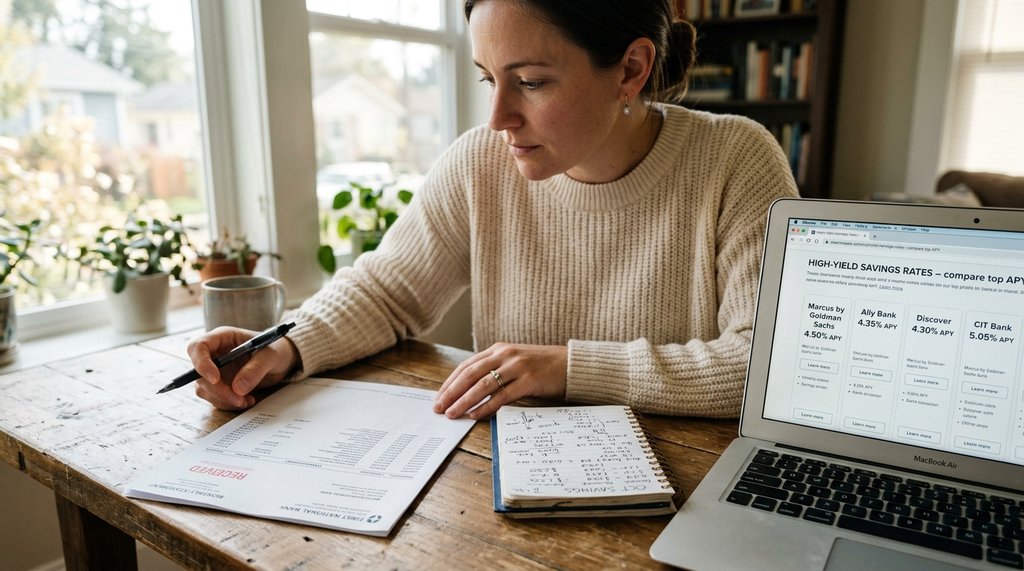
A savings account paying 4.5% APY sounds generous until you run it against the latest inflation figures and realize your real return might be razor-thin.
When a Good Rate Is Not Actually Good
For most of the past two years, high-yield savings accounts have dangled rates between 4% and 5.5%. That range feels impressive compared to the near-zero era of 2021. But a rate does not exist in a vacuum. What matters is whether it clears inflation, which has been running stubbornly around 3.1% through mid-2026.
Do the math simply: a 4.2% APY minus 3.1% inflation leaves a real return of about 1.1%. On a $10,000 balance, that is roughly $110 of genuine purchasing-power gain per year, not $420. Many savers still assume the headline number is their actual gain, and that gap in thinking can lead to complacency about where their cash sits.
The Fed Pause and What It Means for Your Account
The Federal Reserve held rates steady through most of the first half of this year, which means the dramatic rate cuts many analysts predicted in late 2025 mostly did not materialize. The result is a strange middle ground: rates are high enough to attract attention but have quietly slipped from their 2024 peaks at many institutions. Try the annual percentage yield calculator to see your own numbers.
Several online banks that were advertising 5.1% APY in early 2025 have nudged their rates down to 4.3% or 4.5% without much fanfare. If you set up automatic transfers into a high-yield account a year ago and have not checked since, there is a real chance your rate has dropped and you did not notice. A quick check with an annual percentage yield calculator can show you exactly what your current rate compounds to over 12 months, and whether it still clears the inflation bar.
Tax Drag: The Number Nobody Advertises
Even if your APY beats inflation, the IRS takes a cut. Interest income from savings accounts is taxed as ordinary income. For someone in the 22% federal bracket, a 4.4% APY becomes about 3.43% after federal tax alone. Add a state income tax of, say, 5%, and the after-tax yield drops closer to 2.97%. That still beats inflation by a narrow margin, but the cushion is thin.
The practical takeaway is to think in after-tax, after-inflation terms whenever you evaluate a savings rate. A high-yield account is not a bad place for an emergency fund or short-term cash reserve. It just is not a wealth-building engine on its own, which is worth understanding before you park a large windfall there instead of considering alternatives like I-bonds or short-term Treasuries.
A Worked Example to Make It Concrete
Suppose you have $25,000 in a high-yield savings account with a nominal rate of 4.25%, compounded daily. After one year, that account grows to approximately $25,000 times 1.04343, landing around $26,086. That is $1,086 in interest. After 22% federal tax, you keep about $848. With inflation at 3.1%, your $25,000 would need to grow to $25,775 just to maintain purchasing power. So your real, after-tax gain is roughly $73 on $25,000, or about 0.29%.
That is not zero, and it is certainly better than a checking account paying nothing. But knowing the real number changes how you think about opportunity cost. The next time a bank advertises a new high rate, it is worth spending two minutes with an accurate annual percentage yield calculator to model your specific balance, compounding schedule, and tax situation before deciding it is the right home for your money.