
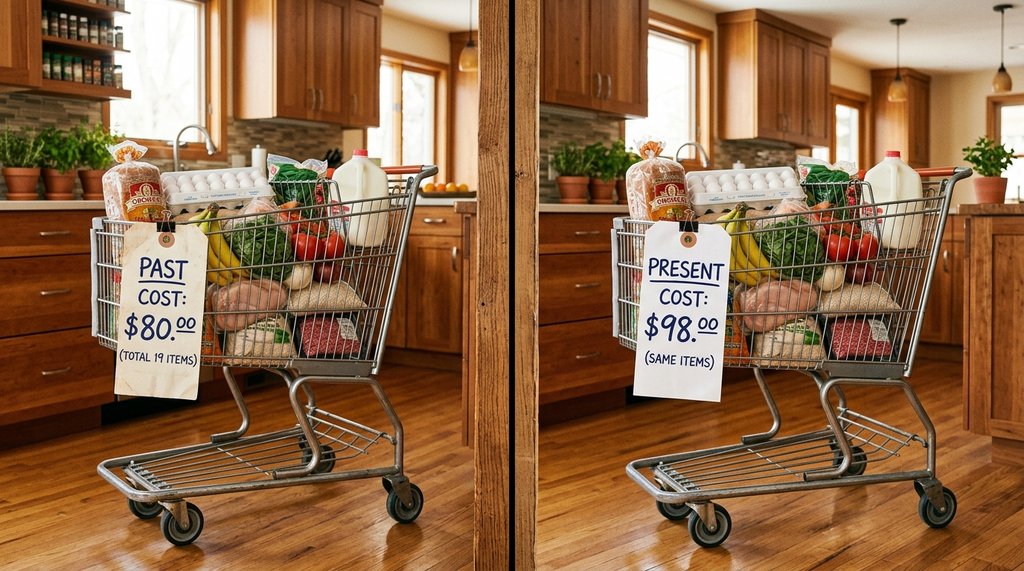
Why Your 2021 Salary Feels So Much Smaller Now
A pay raise that looks generous on paper can quietly shrink your standard of living if prices rise faster than your paycheck.
The Gap Between Nominal and Real Wages
A lot of workers got meaningful raises between 2021 and 2023. Median wages climbed roughly 15 to 20 percent over that stretch, which sounds like a solid win. The problem is that cumulative inflation over the same period ran close to 19 percent at its peak, meaning many of those raises barely kept pace, and some fell behind entirely.
This is the nominal versus real wage trap. Your bank account shows a bigger number every month, but if a bag of groceries that cost $80 in early 2021 now costs $98, the number on your pay stub is doing less work than it used to. Understanding this gap is not just an economics-class exercise; it changes how you should think about job offers, contract renewals, and even Social Security projections.
What Most People Get Wrong About "Keeping Up With Inflation"
The common misconception is that matching the annual CPI number each year is enough. It is not, because inflation compounds just like interest does. A 7 percent spike one year followed by a 4 percent rise the next does not mean you need an 11 percent total raise; you need closer to 11.3 percent just to stay even. Those small compounding differences add up to real money over five or ten years. Try the inflation adjusted value calculator to see your own numbers.
There is also a selection problem with headline CPI. The index reflects a broad basket of goods, but your personal spending pattern may weigh heavily toward categories like rent, childcare, or healthcare, all of which have outpaced general inflation in most recent years. Someone paying $2,200 a month in rent in a mid-tier city is likely experiencing an effective personal inflation rate several points above the headline figure.
Running the numbers on a specific dollar amount, across a specific time window, is the only way to get an honest answer. An inflation adjusted value calculator does exactly that, letting you plug in a starting amount, a start year, and an end year to see what that money is actually worth at the finish line.
A Worked Example: The $65,000 Salary Test
Say you earned $65,000 in 2019 and were offered $75,000 this year after a few lateral moves. That is a $10,000 nominal raise, nearly 15 percent. But run 2019 dollars through to mid-2026 using cumulative CPI data and that original $65,000 is worth roughly $81,000 in today's dollars. Your $75,000 offer is actually a real-terms pay cut of about $6,000 per year.
This kind of calculation matters especially now, when wage growth has cooled but the price levels locked in during the 2022 to 2023 surge have not reversed. Prices rarely fall back to where they were; they just stop climbing as fast. So the baseline has permanently shifted, and any salary comparison that ignores that shift is comparing apples to oranges.
When This Calculation Actually Changes a Decision
Job offers are the obvious use case, but the inflation adjustment logic applies in several other practical moments. Freelancers and contractors setting rates for multi-year projects should build in an annual escalator rather than quoting a flat fee, because a contract signed today at $10,000 per month will be worth noticeably less in purchasing power by year three if inflation holds at even 3 percent.
Retirees relying on fixed pension income face the same math in slow motion. A pension that felt comfortable at retirement can erode significantly over a decade if it lacks a cost-of-living adjustment. Running those projections forward, not just backward, helps retirees plan supplemental income needs before a shortfall becomes a crisis.
Estate planning is another overlooked context. An inheritance or gift that felt substantial in dollar terms a decade ago may be far more modest in real terms today. Knowing the inflation-adjusted figure helps heirs and financial planners set realistic expectations rather than anchoring to a nominal number that no longer reflects actual purchasing power.