
How Income-Driven Repayment Quietly Extends Your Loan by Years
Signing up for an income-driven repayment plan feels like relief, but it often turns a 10-year debt into a 20-year one.
The payment that sounds affordable but costs a fortune
Income-driven repayment (IDR) caps your monthly bill at a percentage of your discretionary income, typically somewhere between 5% and 10% depending on the plan you're on. For a teacher earning $42,000 a year in a high-cost city, that can mean a payment of $150 or less. That feels manageable. The problem is what happens in the background.
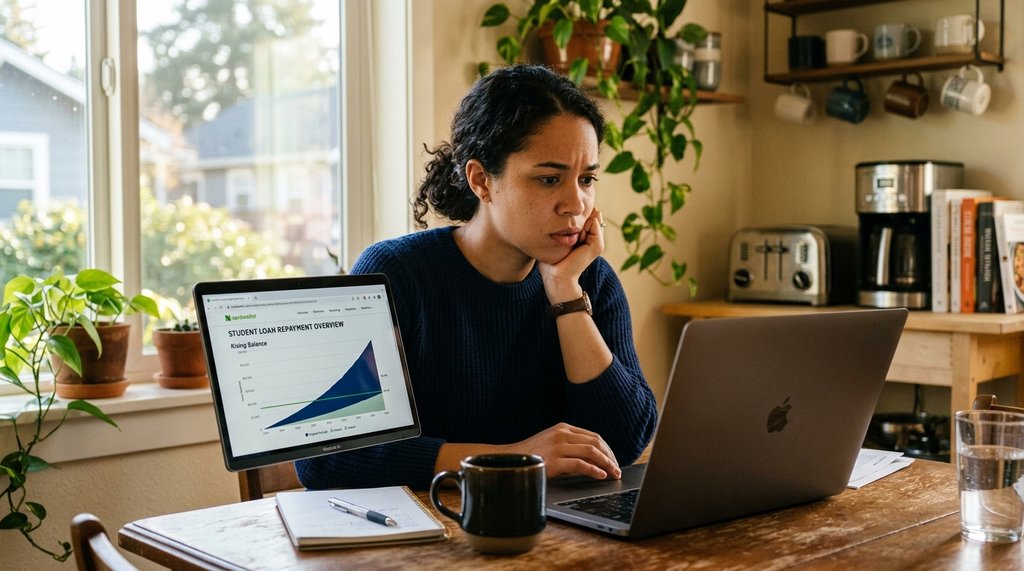
When your payment is smaller than the interest your loan generates each month, your balance either grows or stays flat. A $35,000 loan at 6.5% accrues roughly $190 in interest every month. A $150 payment covers less than 80% of that interest. After 12 months of on-time payments, you may owe more than when you started.
Why the 20-year forgiveness promise is not a free lunch
IDR plans do eventually forgive the remaining balance after 20 or 25 years of qualifying payments. Many borrowers treat that as a safety net and stop thinking about the total cost. But the forgiven amount has historically been treated as taxable income by the IRS, and unless current tax rules change again before your forgiveness date, you could face a tax bill in the tens of thousands in the year your loans are wiped out. Try the student loan payment calculator to see your own numbers.
Run the numbers on a $50,000 balance forgiven after 25 years. If your marginal tax rate is 22%, that single-year income spike could cost $11,000 or more. That is a lump sum due in April, not spread over a comfortable repayment schedule. Borrowers who plan for this years in advance by setting aside money in a taxable account tend to handle it. Those who discover it in the final year typically scramble.
The math also assumes your income stays low enough to qualify for a reduced payment throughout the full repayment window. A promotion, a spouse's income, or a side business can push your required payment up sharply, eroding the very savings that made the plan attractive in the first place.
When IDR makes sense versus when it traps you
IDR is genuinely the right call for specific situations. Public service employees working toward Public Service Loan Forgiveness after 10 years get forgiveness tax-free, and a lower monthly payment means more take-home cash during a decade that often involves modest nonprofit or government salaries. For those borrowers, minimizing payments is an actual strategy, not just a coping mechanism.
For everyone else, the decision depends on one number: how your monthly payment compares to the interest that accrues. If your income-driven payment covers all the interest and chips away at principal, you are in decent shape even on a longer timeline. If it does not cover the interest, you are borrowing time at a literal cost. A student loan payment calculator lets you model both scenarios side by side, entering your actual balance, rate, and income-driven payment amount to see exactly how long payoff takes and what the total interest bill looks like.
Most financial advisors suggest treating IDR as a temporary tool, not a permanent plan. Refinancing to a shorter term when income grows, making extra payments during higher-earning months, or switching from IDR to the standard 10-year plan after a raise are all moves that can cut total interest paid by thousands.
One quick calculation that changes the conversation
Take your current IDR payment and subtract your monthly interest charge. If the result is negative, your balance is growing. If it is positive, you are making real progress. That single subtraction tells you more about your repayment health than your servicer ever will in a routine statement.
Borrowers who do this math for the first time are often surprised. A $200 payment on a loan generating $240 of monthly interest is not making a dent; it is a slow leak. Understanding that gap is what drives people to act, whether that means requesting a pay raise, picking up extra hours, or simply automating an extra $50 a month toward principal. Small changes applied consistently over a decade can easily save $8,000 to $15,000 in interest.