
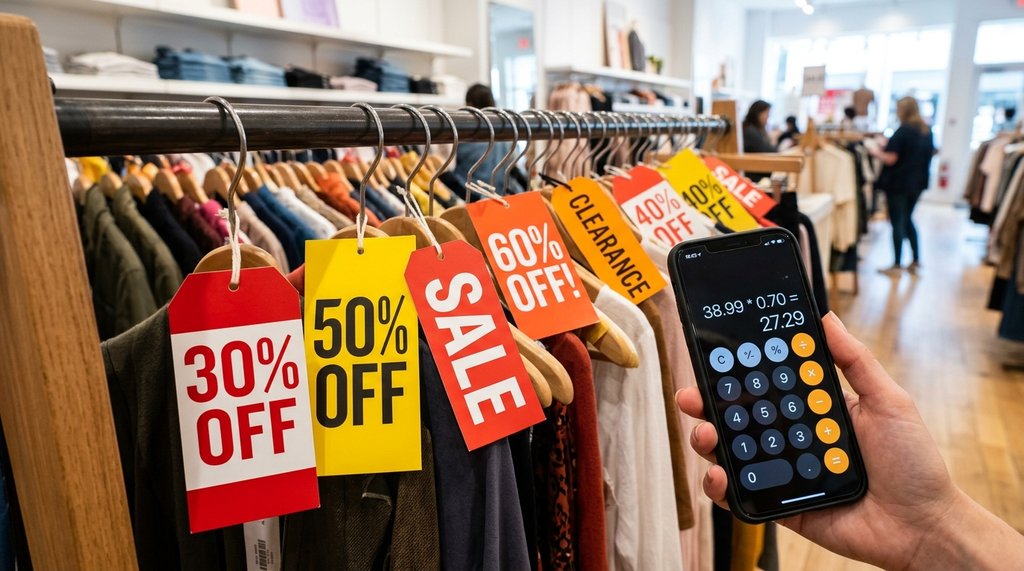
Why Most People Get Sale Discounts Wrong at Checkout
That '40% off' tag looks like a great deal until you realize you have been doing the math backwards the whole time.
The Backwards Discount Mistake Most Shoppers Make
Here is the error that quietly drains wallets at checkout. A jacket is marked down from $120 to $80. Many shoppers mentally calculate the savings as $40 divided by $80, arriving at a 50% discount. Wrong. The correct method divides the savings by the original price: $40 divided by $120 equals 33%. That is a big difference in perceived value.
This mistake matters more than ever heading into the autumn retail season, when stores roll out stacked promotions with language like '40% off, then an extra 20% at the register.' Those two discounts do not add up to 60%. They multiply: you keep 60% of the price, then keep 80% of that, landing at 52% off. Knowing this before you tap your card is genuinely useful.
When Percentage Points and Percentages Are Not the Same Thing
A savings account rate climbing from 4% to 5% is a one percentage point increase, but it is a 25% increase in the yield itself. Banks and lenders count on consumers conflating these two measures. A rate described as 'up 1%' sounds small. A rate 'up 25%' on your interest earnings sounds enormous. Both describe the exact same change. Try the percent calculator to see your own numbers.
The same confusion shows up in credit card cash-back comparisons. Switching from a 1.5% card to a 2% card might seem trivial, but on $30,000 of annual spending that is a difference of $150 in real money. Running the numbers on a reliable percent calculator takes about ten seconds and makes the decision obvious.
Tax season brings its own version of this trap. A deduction that reduces your taxable income by $2,000 does not reduce your tax bill by $2,000. If your marginal rate is 22%, the actual tax saving is $440. People frequently overestimate deductions because they confuse a percentage of income with a percentage of tax owed.
How Stacked Retail Promotions Really Work This Fall
September is historically one of the heavier promotional months in North America, with back-to-school clearance blending into early holiday preview sales. Stores have grown sophisticated about layering discounts in ways that sound generous but are mathematically modest.
A common format: 30% off the sticker price, plus an additional 15% for loyalty members. Shoppers add those and expect 45% off. The actual saving is 40.5%, because the second discount applies to the already-reduced price, not the original. On a $200 purchase the difference is $9, which is not nothing when you are buying multiple items.
The fastest way to check any of these scenarios on the spot is to use a straightforward percent calculator. Type in the original price, apply the first discount, then apply the second to the new total. You get an honest picture in seconds, no mental gymnastics required.
A Quick Framework for Checking Any Percentage Claim
Three questions cut through almost any percentage confusion. First, percentage of what? The base number matters enormously. Second, is this a percentage or a percentage point? Interest rate moves are almost always stated in points, not proportional change. Third, are discounts sequential or simultaneous? Sequential discounts compound; simultaneous ones usually do not.
Running a two-minute check before any significant purchase or financial decision is a habit that pays off repeatedly. The math is not hard, but it is easy to shortcut under time pressure in a store or during a fast-moving negotiation. A tool that handles the arithmetic removes one variable from an already-busy moment.