
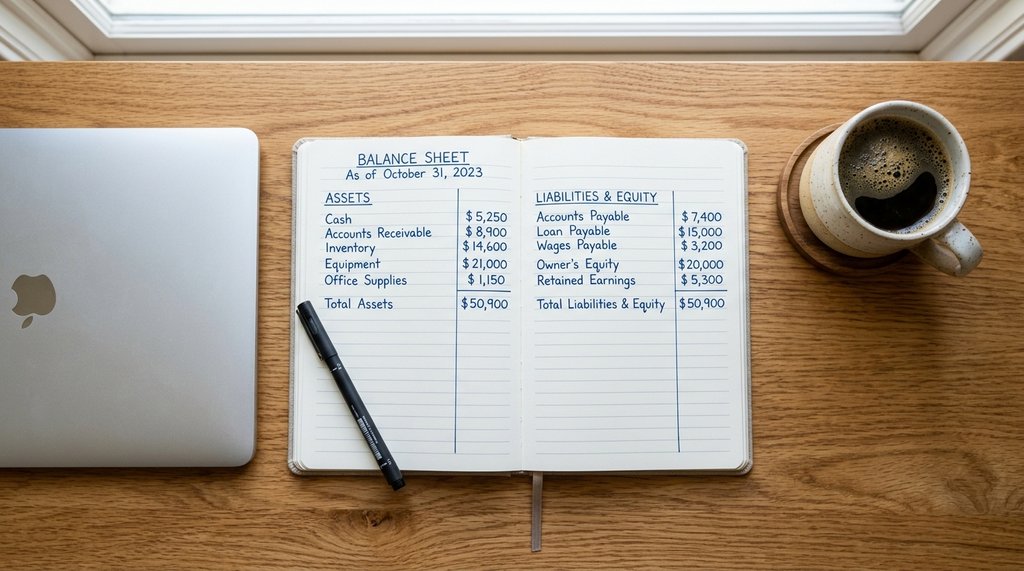
Why Your Net Worth Is Probably Higher Than You Think
A surprising number of people shave tens of thousands of dollars off their own net worth simply by forgetting what counts as an asset.
The Assets People Forget to Count
Most people remember to list their savings account and maybe their home equity. But vested 401(k) balances, HSA funds, the cash value inside a whole life insurance policy, and even prepaid college plan accounts all belong on the asset side of the ledger. Miss two or three of those and you could be underestimating your wealth by $40,000 or more.
With stock markets having recovered sharply through 2025 and early 2026, employer-matched retirement accounts have grown considerably for many workers. If you haven't logged into your brokerage or HR portal in a few months, the figure sitting there may genuinely surprise you. Taxable brokerage accounts, vested RSUs, and crypto holdings round out a category most people either ignore or mentally discount.
How Liabilities Distort the Picture in Both Directions
The flip side is that people often overcount their debts. A car loan with 18 months left is a smaller liability than the original sticker price. What matters is the current payoff balance, not what you borrowed. The same logic applies to mortgages: your liability is today's remaining principal, while your asset is today's market value of the home. The gap between those two numbers is your equity. Try the net worth calculator to see your own numbers.
Student loans deserve special attention in late 2026. Several income-driven repayment programs have seen balance adjustments and forgiveness tranches processed over the past year. If you haven't pulled a fresh payoff quote from your servicer, your actual loan balance may be lower than the number in your head. Plug in accurate figures and the net worth shift can be immediate and meaningful.
Credit card balances are the sneakiest liability of all. They fluctuate month to month and people often recall a rough estimate rather than the actual statement balance. A few hundred dollars of rounding error across three cards is negligible, but four-figure balances rounded down can meaningfully inflate a net worth calculation.
Why Net Worth Beats Income as a Financial Health Signal
Salary tells you about cash flow; net worth tells you about resilience. Two households earning $95,000 a year can have wildly different financial stability depending on whether one carries $180,000 in assets and $40,000 in debt or the reverse. Lenders, financial planners, and yes, your own sense of security all benefit from knowing the balance sheet number, not just the income line.
A concrete net worth figure also makes goal-setting far more actionable. Saying you want to retire comfortably is vague. Saying you need to close a $320,000 gap between your current net worth and your target retirement number gives you a specific savings rate to reverse-engineer. Use a net worth calculator to establish the baseline, then revisit it every quarter to track momentum.
Getting the Number Right Before Year-End Tax Planning
September is an underrated month for financial housekeeping. You still have the fourth quarter to harvest tax losses in a brokerage account, top up an HSA, or make catch-up contributions to a retirement plan before the calendar flips. None of those moves are obvious unless you first know what you actually own and owe right now.
Running an honest accounting of your assets and liabilities also surfaces opportunities you might otherwise miss. A highly appreciated stock position buried in a taxable account, for example, could be a candidate for charitable gifting before December 31, eliminating capital gains tax entirely. You cannot spot that opportunity without a clear asset inventory. That is exactly what a thorough net worth snapshot provides.