
How Inflation Quietly Erodes Your Retirement Savings
A savings balance that looks comfortable today can feel painfully thin twenty years from now, and inflation is almost always the culprit nobody planned for.
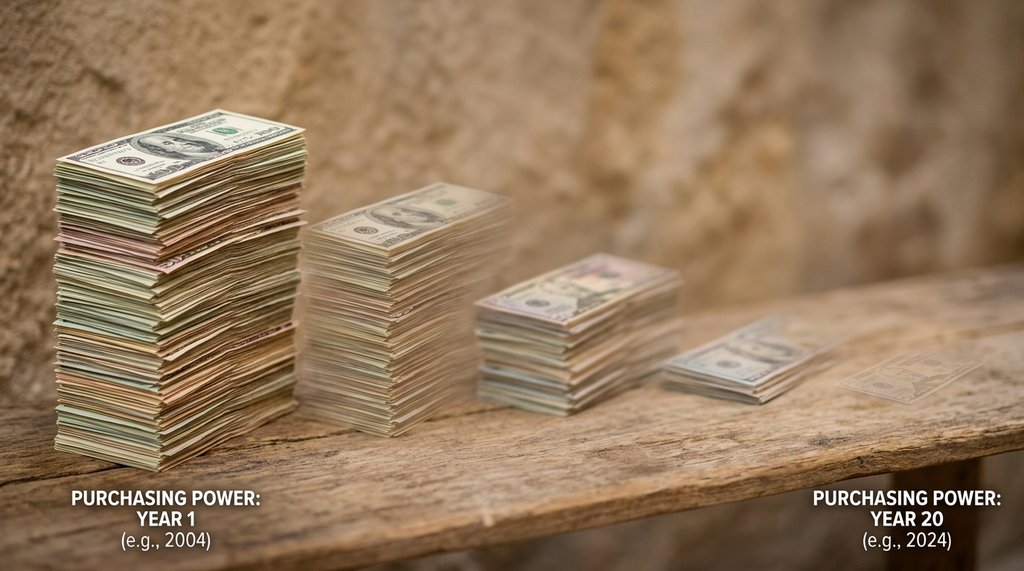
What 3% Inflation Does to $1 Million Over 20 Years
Most people anchor their retirement goal to a big round number, say $1 million, and feel confident once they hit it. But $1 million in 2025 dollars is only worth about $554,000 in 2045 dollars if inflation runs at a modest 3% per year. That is not a worst-case scenario; it is roughly the long-run average for the United States.
The math compounds fast. At 3% inflation, prices double every 24 years. So a retiree who needs $5,000 a month to cover expenses today will need closer to $9,000 a month by 2049 just to maintain the same standard of living. If your savings projections never accounted for that gap, you are essentially planning to take a permanent pay cut in retirement.
Why Fixed Income Sources Make the Problem Worse
Social Security does include a cost-of-living adjustment, but it tracks the Consumer Price Index for Urban Wage Earners, which tends to underweight healthcare costs. Retirees spend a disproportionate share of their budget on medical care, and healthcare inflation has averaged closer to 5% annually over the past decade. That gap between your COLA raise and your actual rising costs chips away at purchasing power every single year. Try the retirement savings calculator to see your own numbers.
Pensions and annuities with fixed monthly payments offer no adjustment at all. A $2,000 monthly pension that felt generous at 65 covers dramatically less ground at 80. Many retirees discover this only after they have already locked in their income streams and spent down the flexible assets that could have compensated.
Building an Inflation Assumption Into Your Target Number
The fix is to model inflation explicitly before you set your savings target, not after. That means using a retirement savings projector that lets you input both an expected investment return and a separate inflation rate, then shows you results in real, today-equivalent dollars rather than nominal future dollars. The difference can be staggering. A projection showing $1.4 million at retirement sounds great until you see that it translates to only $780,000 in today's spending power.
A practical approach: set your spending goal in today's dollars, then use a retirement savings calculator to find the nominal portfolio size you actually need, given your assumed inflation rate and time horizon. If you plan to retire in 30 years and assume 3% inflation, your target in future dollars is your today-target multiplied by roughly 2.4. Running that number through a tool that accounts for investment growth and withdrawal rates gives you a far more honest picture than guessing.
Adjusting Your Strategy, Not Just Your Target
Knowing the inflation-adjusted target is step one. Step two is choosing assets that have historically kept pace or outpaced inflation. Equities, Treasury Inflation-Protected Securities, and real estate have all served as partial hedges over long periods, while cash and fixed-rate bonds typically fall behind. Keeping too large a cash cushion in the years leading up to retirement can actually increase inflation risk, not reduce it.
It also helps to revisit your projections every two or three years rather than setting a goal at 35 and checking back in at 64. Inflation assumptions, expected returns, and your actual spending habits all shift over time. Small recalibrations early cost you almost nothing. Large corrections close to retirement can require painful trade-offs like delaying your target date or cutting discretionary spending permanently.